Gig Economy & Freelancer Finance: Tax, Insurance & Retirement Planning
 Written by Tanvi Sharma - 2 Days Ago
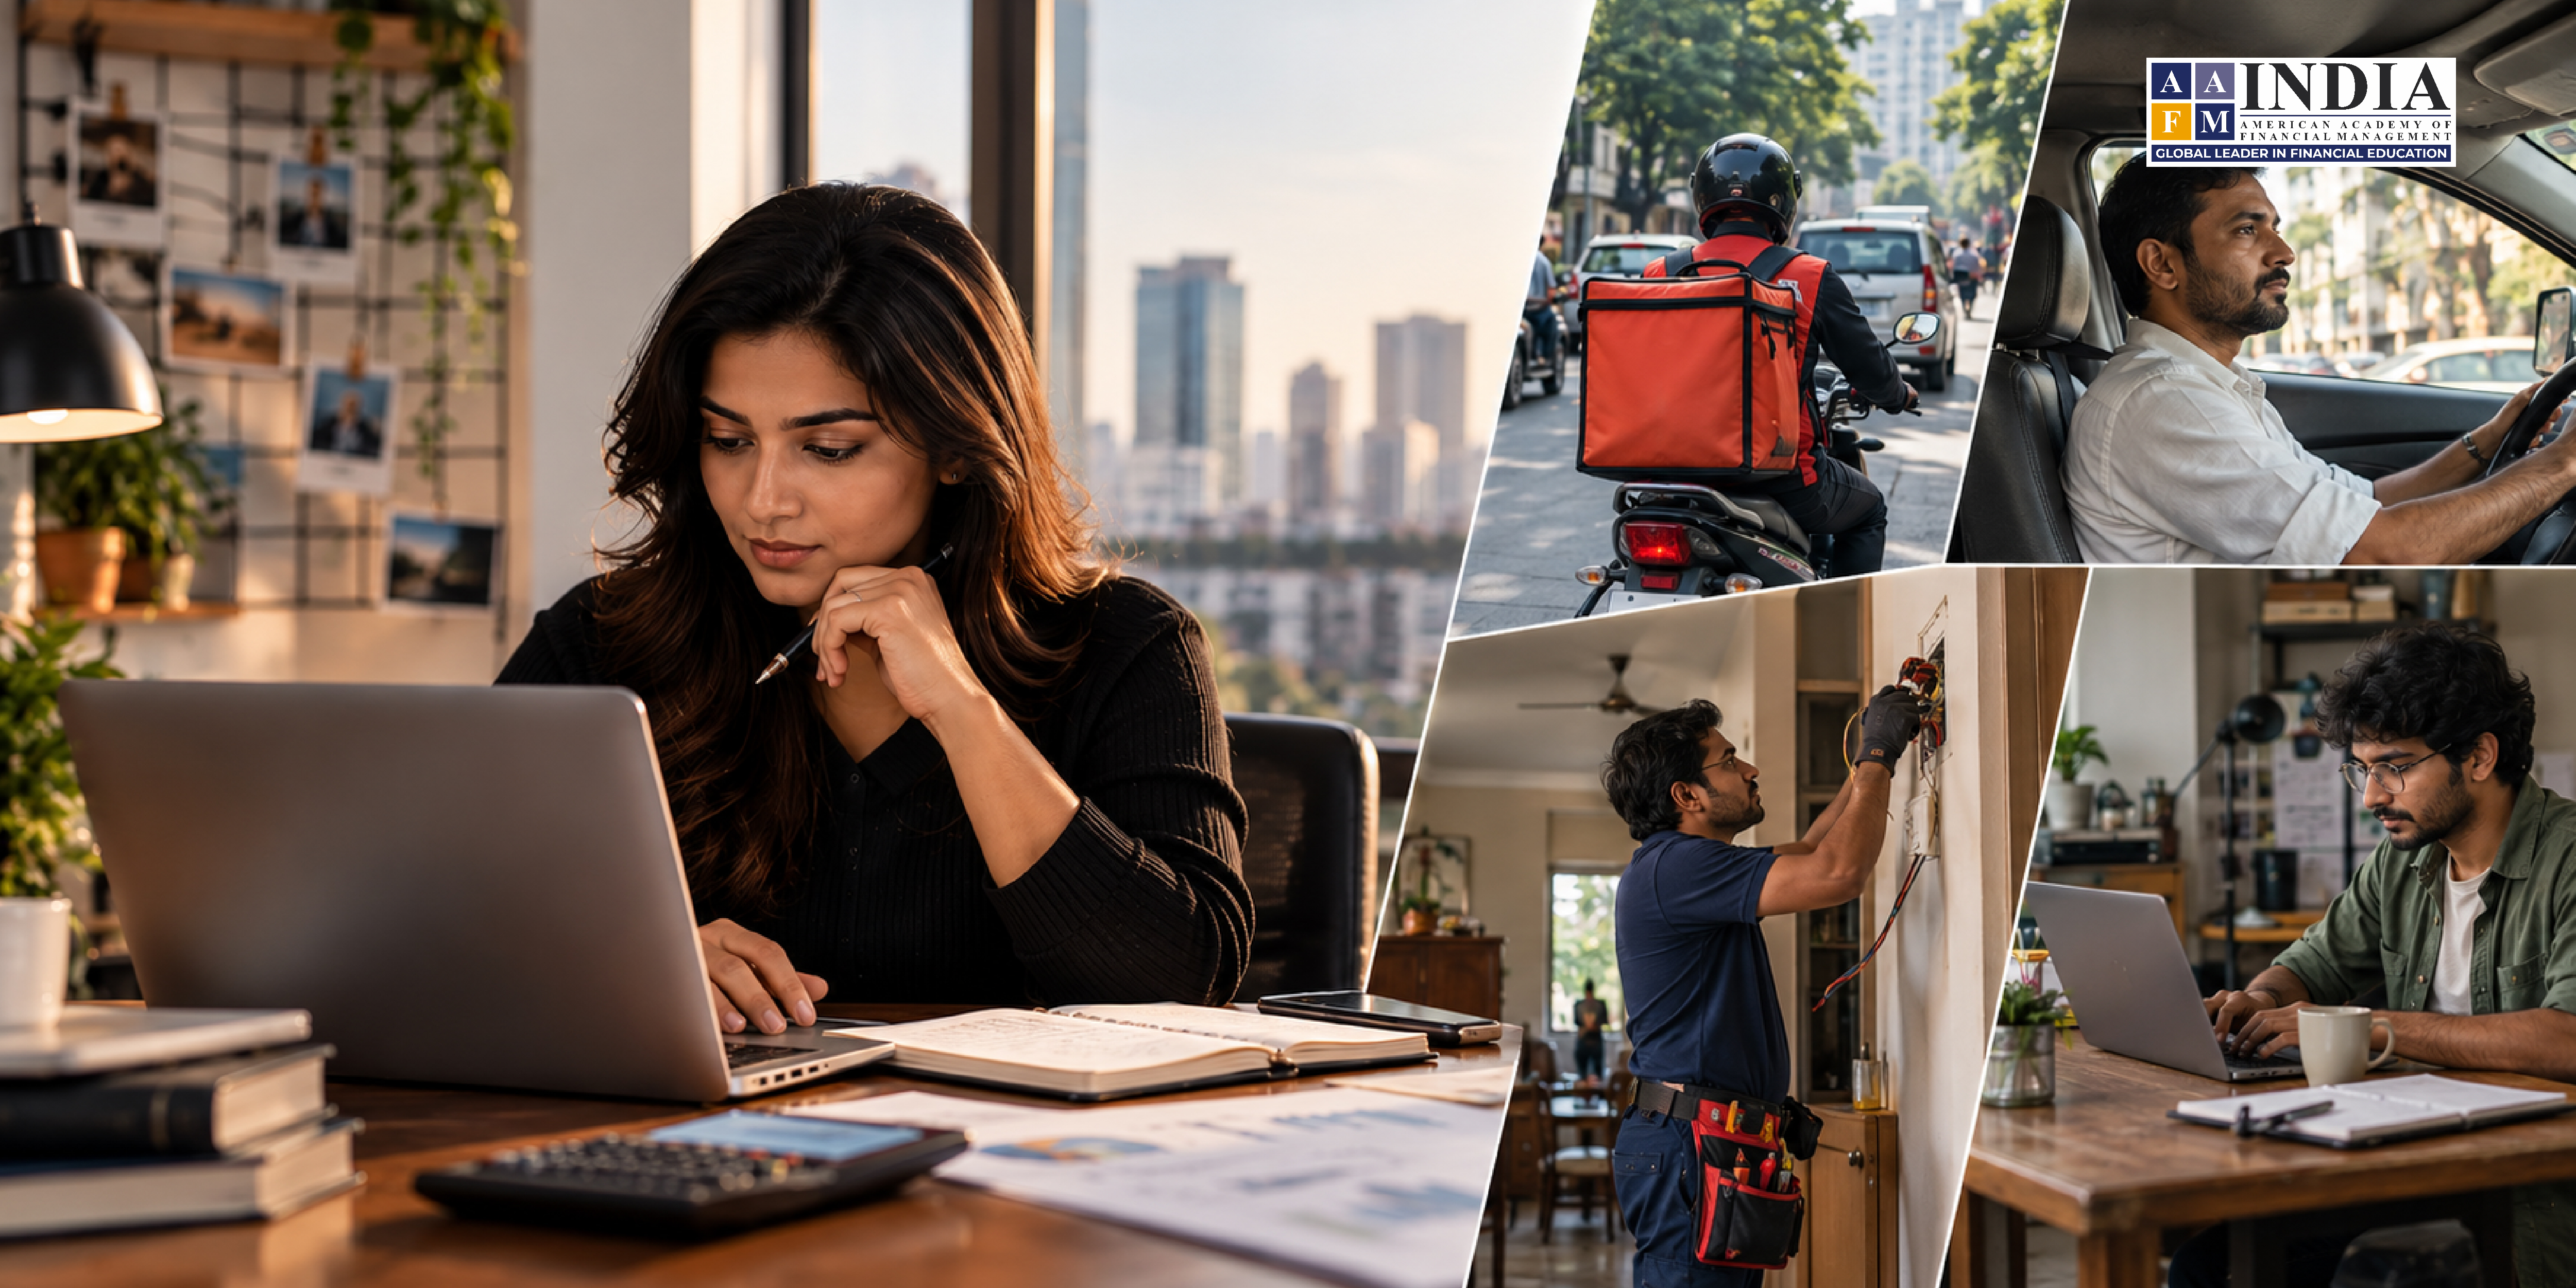
One payment. Three months of work. A dozen places for the money to go.
When Riya finally received ₹60,000 from a client, her first thought was to treat herself to dinner. The freelance designer had spent weeks completing the project and chasing payment.
Then she remembered the rent, software renewal and overdue laptop repair. Another project was being discussed, but its start date—and payment—remained uncertain.
She could afford dinner. What she needed to understand was how much she could spend afterwards.
For many working in the gig economy in India, this is familiar. Each payment must cover everyday expenses while leaving room for taxes, insurance and future savings. Finding that balance starts with understanding your earnings.
Understanding India’s Gig Economy: Freelancers and Platform Workers
Gig Economy includes people who earn from assignments or tasks without being in the employer-employee arrangement. This can be their sole source of income or even a supplement.
Freelancers use their skills in writing, design, programming, and consulting and work either with the client or via platforms. They negotiate rates, timeframes, and payment methods.
Platform Workers, such as delivery workers, cab drivers, or even house service workers get assigned via apps. Their income is based on task requirements, demand, incentives, and platform deductions.
Though there is some intersection between these two groups, payment models are quite different. A designer needs to wait several weeks for an invoice; a delivery worker gets paid every week but spends money on fuel and maintenance.
Financial Planning for Freelancers Starts with Your Real Income
A ₹50,000 payment doesn’t mean ₹50,000 is available for household spending. Software, internet, travel and other work costs come first, alongside any tax still payable. If work expenses total ₹8,000, ₹42,000 remains before tax provisions.
Keep track of these three elements: payments received, business expenditure and money kept aside for taxes. Maintain another record for outstanding invoices because a promise does not solve today’s problem. Having a separate account for business helps in keeping track.
Use a prudent approach to budget based on some months’ figures, including those which were less busy. Include rent, food expenses, EMIs, utilities and any business expense that you can’t avoid. When the month of earnings arrives, keep aside extra money for quiet weeks and increase your budgeting thereafter.
Having an emergency fund is important for freelancers because it takes care of delayed payments, sickness and repair work. Start with one month’s expenses and build up gradually. You will need more money if you have dependants or if there are delays in payments.
Tax Planning for Freelancers and Gig Workers in India
For freelancers in India, income tax usually is on income from business/profession. In the usual method of accounting, eligible costs of work can be deducted from income. Maintain all receipts and take a deduction only for the work part of shared internet/telephone bills.
The platform worker needs to reconcile the earnings reported with the payments made after making deductions. Drivers/delivery partners need to maintain costs related to work. If the platform manages some taxes, it doesn’t take care of income tax of the individual.
Effective tax planning for freelancers and gig workers involves four checks:
- TDS: Client or platform can deduct tax from their payments. It is part of the total tax liability. Verify this from Form 26AS.
- Advance tax: Generally applicable when the estimated tax payable after TDS is ₹10,000 or above. Advance tax payments vary depending on the taxation scheme.
- Presumptive taxation: Presumptive taxation can be applied to eligible business entities and specified professions. The eligibility depends on the activity performed and not by the classification as freelancers or gig workers.
- GST: There is a ₹20 lakh threshold for registration for service providers with special GST provisions for certain platform services.
Compare tax regimes before claiming deductions; benefits depend on the applicable regime and conditions.
Insurance for Gig Workers: Protecting Your Health and Income
If a delivery partner injured his leg, he will be faced with expenses of treatment and time without salary for many weeks. A freelancer who has had surgery has the same situation.
Insurance for gig workers in India should reflect working conditions and family responsibilities.
- Health Insurance: Look at network hospital options, waiting period, room rent caps, and co-pay on claim expenses. Lower premiums often entail conditions that can cause significant expense not to be covered.
- Personal Accident Insurance: More relevant for motorists and delivery partners. Look at accidental death and disability coverage options. Temporary disability is only available as an add-on, based on terms and conditions.
- Term Life Insurance: This is more important if your earnings contribute to those of your parents, spouse, or offspring. This may include the debts, living costs, and dreams of other family members.
The insurance coverage will depend upon the validity of the period, eligibility of the family member, and circumstances when you exit from the platform. Please make sure that you keep your insurance information handy for your family.
Medical cover generally does not replace lost earnings, so an emergency reserve remains essential during recovery.
Retirement Planning When You’re Self-Employed
There is also the matter of finding room in the budget for retirement savings. The idea of waiting until one makes steady income could take decades to realize.
Calculate how much will be needed for the future in terms of housing, food, and medical care, accounting for increases in prices. Include savings already made and the time left to save the balance.
Different products serve different purposes:
- National Pension System (NPS): The scheme is based on investment in various assets, such as equity and debt, with market-driven returns. Review investment options, fees, and withdrawal criteria.
- Public Provident Fund (PPF): This is a government product that can help in securing the stable part of long-term investments. It matures after 15 full years from the end of the first year.
- Diversified mutual funds: These can serve as an addition to retirement investments. Equity funds are volatile and need a long period, debt funds have their own risks too.
Contribute an amount manageable during ordinary months, adding more when earnings allow. Review annually as income and responsibilities change. Keep retirement savings separate from the reserve used between projects.
Government Schemes for Gig Workers
Schemes by the government for gig workers offer basic security depending on their age, income level, and social security status.
- Pradhan Mantri Suraksha Bima Yojana (PMSBY): Provides coverage against accidents, death, and disability. Individuals whose accounts are banked in the age group of 18-70 years can enroll with automatic deduction of premium.
- e-Shram: Helps eligible gig economy and platform workers in availing themselves of welfare schemes. Enrollment does not automatically grant all benefits, and there are individual eligibility criteria.
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY): Provides Rs. 2 Lakh of life insurance coverage, depending on the terms of the agreement. Eligible individuals can enroll from the age group of 18-50.
- Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM): Pension scheme for eligible unorganized gig workers from the age group of 18-40 years with an income level of up to ₹15,000. It provides a pension of ₹3,000 per month from the age of 60.
Verify eligibility through official portals or participating banks. Update nominees and maintain funds for renewals or contributions. Benefits may meet only part of your family’s needs.

Read More :- How to Become an Estate Planning Consultant in India: A CTEP Career Guide
Conclusion
Independent working allows you to manage your career path yourself. By planning you are able to maintain the sustainability of your independent business amidst stress.
Know your income, prepare for your taxes, protect your family and save. Let your plan evolve with you.
Every payment reflects your time and effort.
Give part of it a purpose beyond the next bill—towards a future where working remains a choice.
Frequently Asked Questions
Q1. How can freelancers budget with irregular income?
Ans. Base essential spending on conservative earnings after work expenses. Retain surplus from better months for quieter periods.
Q2. Is TDS the final tax on freelance income?
Ans. No. It is a credit towards final liability. Your total income and applicable provisions determine whether additional tax or a refund is due.
Q3. Is platform-provided insurance enough?
Ans. Review coverage, exclusions and eligibility criteria. More insurance may be required for medical expenses, disability and family-related needs.
Q4. Can self-employed people save for retirement through NPS?
Ans. Eligible people can enroll voluntarily. Evaluate investment risk, fees, and withdrawal terms.
Q5. Does e-Shram registration automatically provide insurance or a pension?
Ans. No. Each scheme has separate eligibility, enrolment and contribution requirements.
Author by
Comments (0)
Search
Popular categories
Wealth Management
14Finance
12Financial Planning
7Finance Certifications
5Investing
4Estate Planning
3Latest blogs
Gig Economy & Freelancer Finance: Tax, Insurance & Retirement Planning
2 Days Ago 0 37
ESG Investing in India: A Guide for Investors & Wealth Managers
6 Days Ago 0 82
How to Become an Estate Planning Consultant in India: A CTEP Career Guide
7 Days Ago 0 102
Write a public review