Which Is Better: PPF, NPS or EPF? Returns, Risk & Tax
 Written by Tanvi Sharma - 17 Hours Ago
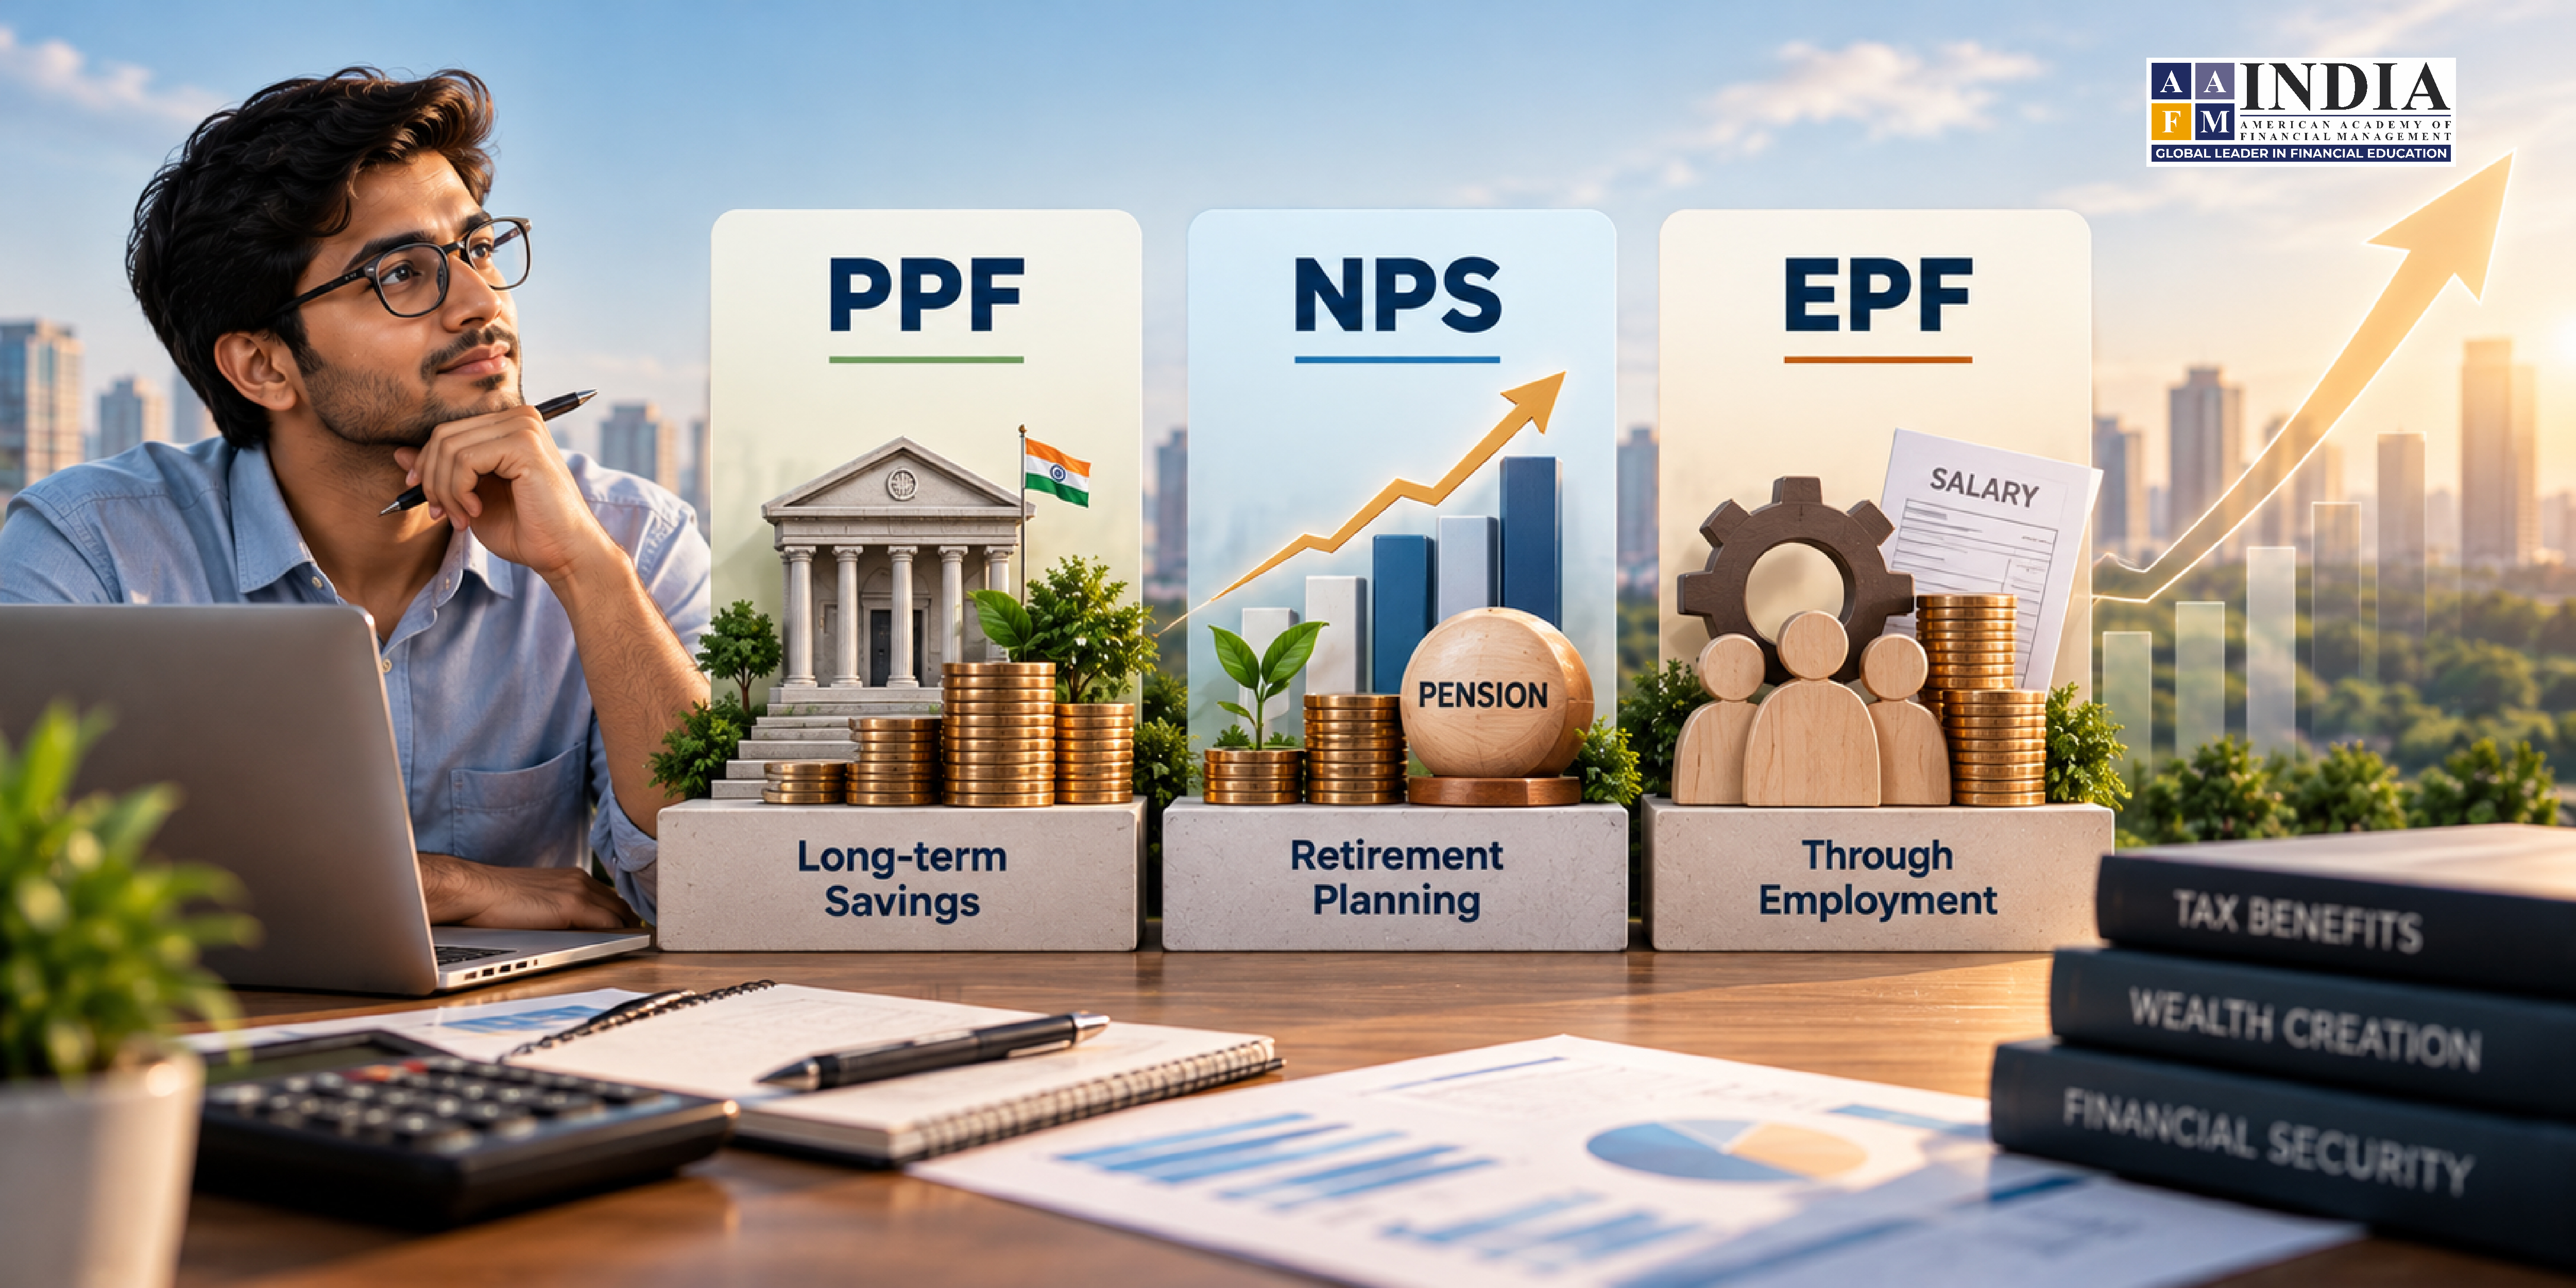
PPF vs NPS vs EPF: Comparing India's Long-Term Savings Instruments
When Rohan received his annual salary hike, he decided to save a little more each month. But choosing where to put that money brought more questions than he expected.
His father suggested PPF, an account he had trusted for years. A colleague recommended NPS for retirement. Rohan already had EPF deductions on his salary slip, so he wondered whether he needed all three—and what each would add to his savings.
It is a common starting point for retirement planning in India. One hears advice from one’s family, engages in discussions in one’s place of work, and starts saving even without full knowledge of the instrument.
PPF, NPS and EPF are all effective ways to create savings over a longer period, but the key difference lies in the manner in which your investments grow, risk level, tax benefits and the time frame in which you can withdraw the money.
Here is a comparative analysis of PPF, NPS and EPF to get a clearer idea about them.
Understanding PPF, NPS and EPF
PPF (Public Provident Fund) is a government-backed scheme available through authorised banks and post offices. You fund the account without choosing underlying investments.
NPS (National Pension System) Tier I invests through pension funds in equities, corporate bonds and government securities. You can choose a pension fund and investment approach within scheme rules.
EPF (Employees’ Provident Fund) builds savings through eligible employment, using employee and employer contributions. For eligible members, part of the employer’s share funds the separate Employees’ Pension Scheme (EPS).
(Note: This comparison covers NPS Tier I. Tier II is an optional investment account with flexible withdrawals and generally no tax deductions.)
PPF vs NPS vs EPF: Key Differences at a Glance
|
Feature |
PPF |
NPS Tier I |
EPF |
|
Primary Objective |
Building long-term savings |
Building a retirement corpus and supporting retirement income |
Building retirement savings through employment |
|
Mode of Participation |
Open an account independently |
Join individually or through an employer |
Through eligible employment |
|
Source of Contributions |
Account holder |
Subscriber and/or employer |
Employee and employer |
|
Nature of Returns |
Government-notified interest |
Market-linked investment returns |
Interest declared for each financial year |
|
Investment Choice |
No choice regarding investments |
Selection of pension funds and investment strategy, as per scheme guidelines |
There is no personal selection of investment vehicles |
|
Lock-in Period / Maturity |
Fifteen years from the financial year-end of the opening of the account |
In accordance with All Citizen, normal exit shall be available either after the age of 60 or 15 years of subscription, whichever is earlier, subject to scheme requirements. |
No specific time for account duration; final settlement shall be subject to retirement or cessation of employment conditions |
|
Partial Withdrawals / Advances |
Withdrawal of limited amounts after five years from the close of the first financial year, within set limitations |
Withdrawals for certain purposes, based on eligibility, limits, and frequencies |
Advances for qualifying needs such as medical treatment, housing and education, subject to eligibility and limits |
|
Premature Closure / Early Exit |
Allowed under certain conditions after the stipulated time period with interest deduction |
Early withdrawal usually necessitates an increased proportion of the annuity, except in cases involving small sums |
Final settlement prior to retirement shall be based on employment-related terms; job relocation normally provides for transfer |
|
Maturity / Normal Exit Withdrawals |
Withdrawal at the time of maturity or else renewal after five years with additions to savings |
For non-government subscribers, typically 80% as a lump sum and 20% as an annuity; there are special rules for smaller balances |
Final settlement EPF payable from accumulated balance |
|
Retirement Payout Structure |
It is the decision of the account holder as to how he uses the savings made |
Lump sum and annuity income based on relevant exit provisions |
EPF savings were made; EPS pension scheme is different |
The timing of the provision of the above benefits depends on the withdrawal conditions and the eligibility criteria. PPF allows you to choose how to utilize the maturity amount. The NPS plan may provide both easy availability of the lump sum as well as annuity income.
Contributions and Eligibility: Who Can Invest and How Much?
|
Parameter |
PPF |
NPS Tier I |
EPF |
|
Eligibility |
Eligible resident individuals; accounts for minors may be operated by a guardian |
Eligible salaried and self-employed individuals, including NRIs and OCIs, subject to scheme conditions |
Employees eligible for membership under EPF rules |
|
Minimum Contribution |
₹500 per financial year |
₹500 at account opening; ₹1,000 per financial year |
Generally 12% of applicable wages, subject to statutory provisions |
|
Contribution Ceiling |
₹1.5 lakh per financial year* |
No overall upper contribution limit; tax deductions are subject to separate limits |
Voluntary employee contributions above the prescribed rate are permitted through VPF, subject to applicable rules |
|
Contribution Frequency |
Lump sum or instalments within the financial year |
Flexible individual contributions or employer-facilitated payroll contributions |
Monthly contributions through payroll |
|
Employer Participation |
No employer contribution provision |
Employer contributions permitted under participating workplace arrangements |
Generally 12% of applicable wages, with a portion allocated to EPS for eligible members |
PPF’s ceiling includes contributions to your account and a minor’s account operated by you as guardian. EPF rates and allocations have exceptions. Employers need not match additional VPF contributions. NPS investment limits differ from tax-deduction limits.
Returns and Risks: How Do These Instruments Compare?
Knowing the contribution limits is a starting point. Next, consider how your savings grow and what could affect them.
The Difference in Growth
PPF earns government-notified interest, reviewed quarterly; EPF credits interest declared for each financial year. Both rates can change. NPS invests through pension funds in shares and bonds, with returns depending on allocation, performance and charges.
The Difference in Risk
The PPF and EPF accounts do not display fluctuations in the market on a daily basis. The NPS amounts may fluctuate based on the percentage of equities included. There is also risk in bonds because there is no guarantee on their returns.
The Question They Share
Will your savings keep pace with expenses? Inflation reduces purchasing power across all three.

A PPF vs NPS comparison involves stability and growth potential. An EPF vs PPF comparison involves separately determined interest rates. Tax treatment then affects what you retain.
Tax Benefits of PPF, NPS and EPF
Deductions on Contributions
With the existing tax system, there are certain conditions for income based on which the NPS deduction is allowed. The ceiling amount for all three – PPF deposit, employee EPF contribution, and qualifying personal NPS contribution is ₹1.5 lakh.
If EPF and other eligible payments exhaust the shared ceiling, PPF creates no further deduction.
Under the new regime, these personal contribution deductions are unavailable. Eligible employer NPS contributions remain deductible within applicable limits.
Tax Treatment of Withdrawals
PPF: Interest and withdrawals under scheme rules are exempt.
EPF: Withdrawals are generally exempt after five years’ continuous qualifying service. Earlier withdrawals can attract tax, subject to exceptions. Where employers contribute, interest attributable to employee contributions exceeding ₹2.5 lakh annually is taxable.
NPS: Published tax guidance exempts lump-sum withdrawals up to 60% of the corpus. Permission to withdraw more under exit rules does not automatically extend that exemption. Annuity income is taxable.
How Can PPF, NPS and EPF Work Together?
All three can be used simultaneously by eligible individuals. For instance, one may use the EPF for job savings, the PPF for a maturity-based goal, and the NPS for market-based retirement savings.
The two should be considered together as interest-based savings while evaluating equity investments. Having more accounts means limited access, hence having an emergency fund is essential. In any case before making another investment, evaluate the gap that exists between the savings one already has towards retirement.
One does not have to split contributions equally. It depends on affordability, future savings plans and payment periods.
Read More :- What Are REITs and InvITs in India? A Beginner’s Guide
Conclusion
The money that you save today will influence the decisions that you take tomorrow, right from managing basic expenses to living out your aspirations.
Knowledge of PPF, NPS and EPF will enable you to decide how you can make those savings work for you. PPF gives you government insured savings, NPS gives you market-linked gains and EPF enables you to accumulate savings through employment which qualifies.
Begin by looking at where you stand now, look at the gap and start saving accordingly. Over time, review your plan based on your needs.
It all boils down to being able to have enough financial space to enjoy the days ahead.
Frequently Asked Questions
Q1. Can I hold all three?
Ans. Yes, subject to eligibility.
Q2. Is PPF better than NPS?
Ans. Suitability depends on goals, risk tolerance and access needs.
Q3. Can self-employed individuals open EPF?
Ans. Generally, no; consider eligible PPF or NPS accounts.
Q4. Are new-regime deductions available?
Ans. Generally not for personal contributions; eligible employer NPS contributions qualify within limits.
Q5. Is EPF enough for retirement?
Ans. Assess savings against retirement timing, inflation, healthcare and expected expenses.
Author by
Comments (0)
Search
Popular categories
Wealth Management
14Finance
14Financial Planning
7Finance Certifications
5Investing
4Estate Planning
3Latest blogs
Which Is Better: PPF, NPS or EPF? Returns, Risk & Tax
17 Hours Ago 0 17
What Are REITs and InvITs in India? A Beginner’s Guide
2 Days Ago 0 28
Gig Economy & Freelancer Finance: Tax, Insurance & Retirement Planning
5 Days Ago 0 68
Write a public review